


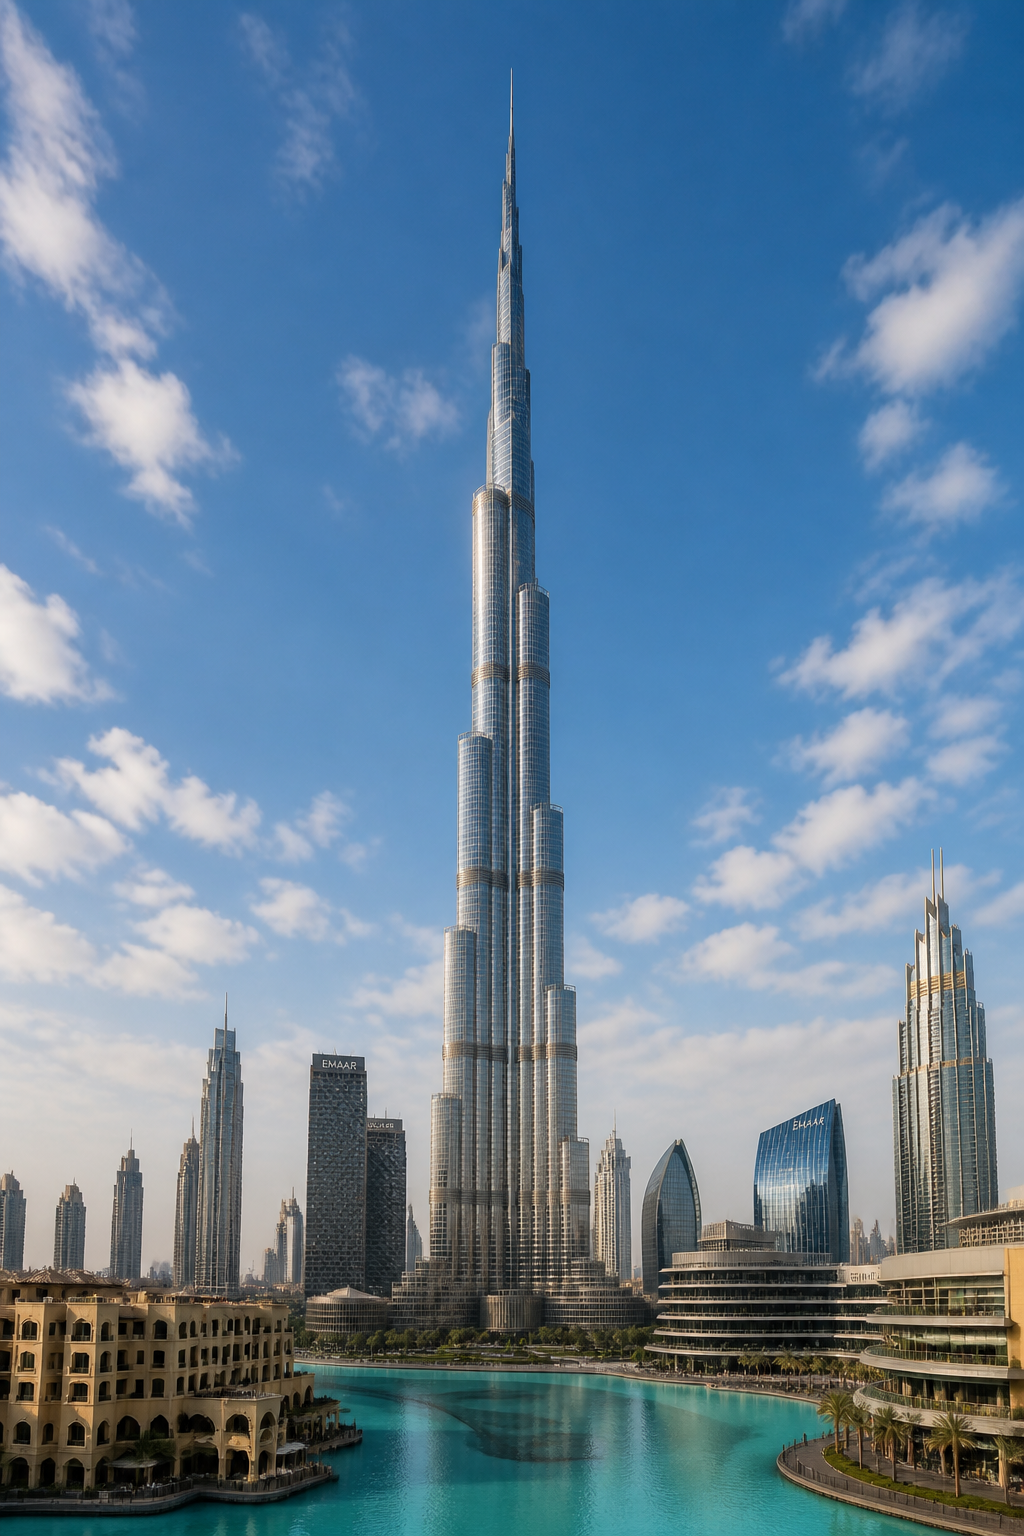














Dubai’s residential property market experienced a notable slowdown in the third quarter of this year, as transaction volumes and values decreased significantly. This shift follows a period of robust growth and reflects increased buyer caution amidst regional uncertainties. Data reveals that residential home sales in Dubai totaled Dh72.6 billion ($19.7 billion) during the three months ending September, marking a substantial 47 per cent reduction compared to the same period in the previous year. Concurrently, the number of transactions fell by 38 per cent, reaching 34,000 over the quarter.
According to a report by property consultants Cavendish Maxwell, this decline underscores a period of reduced market activity, as the registration of property sales began to catch up. Ronan Arthur, director and head of residential valuation at Cavendish Maxwell, noted, “Purchasing activity became more measured, with buyers being more cautious in the weeks and months following the start of the conflict.” This sentiment was largely attributed to regional tensions, triggered by the Iran war that commenced in late February, which prompted a more conservative approach from investors and end-users.
The cooling market contrasts with the preceding years, which saw Dubai’s property sector experience a significant boom. This growth was fuelled by strategic government initiatives, including the introduction of residency permits for retired and remote workers, an expansion of the 10-year golden visa programme, and broader economic diversification efforts across the UAE. These policies attracted a diverse range of international buyers and investors, solidifying Dubai’s appeal as a global real estate hub.
Despite the overall market adjustment, off-plan properties continued to dominate sales activity during the third quarter. These speculative purchases accounted for 65 per cent of the total sales values and an even higher 72 per cent of all property purchases made within the period. Looking ahead, S&P Global Ratings projects that apartment price declines are likely to outpace those of villas, largely due to a robust pipeline of new supply entering the market. This outlook suggests a continued focus on market fundamentals and supply-demand dynamics in the coming quarters.